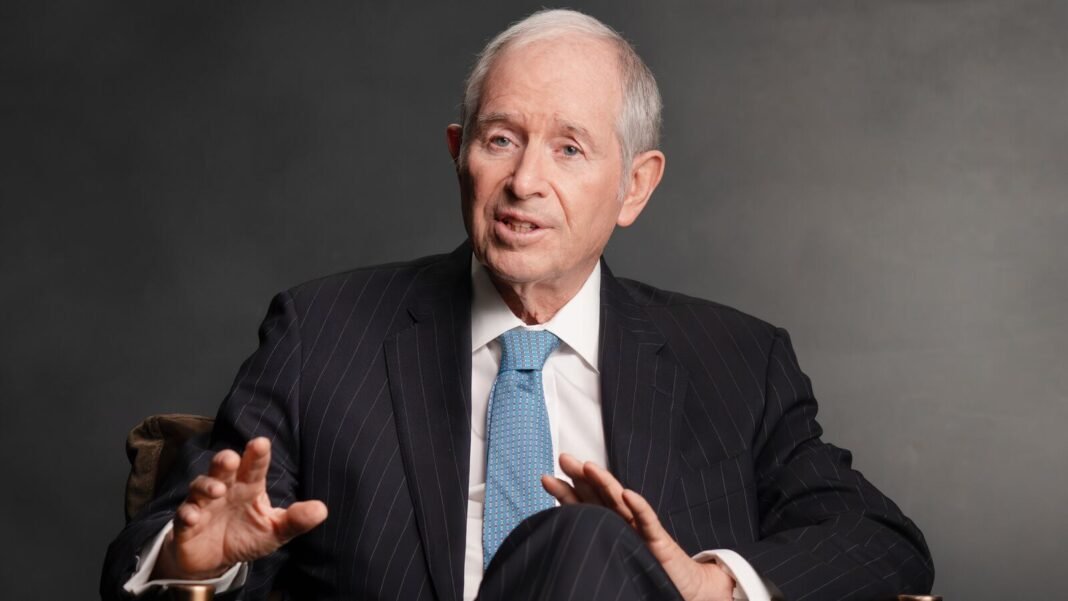
Blackstone expects the share of its assets under management in the Gulf to grow three to four times from current levels by the end of the decade, Chairman and Chief Executive Stephen Schwarzman said.
“I would say it would surprise me if it weren’t three to four times larger from the current level,” Schwarzman told The National in an interview published on Wednesday. He did not give a dollar figure.
The $1.3 trillion alternative asset manager has committed more capital to the Gulf in the past 12 months than at any point in its history, according to the interview.
In July, Blackstone and global partners invested $16 billion in Kuwait Oil Company’s crude oil pipeline network. In April, it teamed up with Dubai Aerospace Enterprise to invest about $1.6 billion a year in aircraft leasing.
Its portfolio company AirTrunk has also struck a $3 billion data center deal with Saudi Arabia’s Humain.
Blackstone opened its first office in Abu Dhabi in 2010. It has since expanded the scope of its Abu Dhabi license, opened an office in Kuwait and is preparing to launch private wealth operations in Dubai.
“We’re going to have offices in pretty much every country,” Schwarzman said.
He said the war involving Iran had changed the region’s risk profile, but that Blackstone invests for the long term.
Schwarzman said Gulf governments would spend heavily to protect their infrastructure over the next two to three years. He said Blackstone anticipates a “very substantial construction boom” as countries move vulnerable infrastructure underground.
The International Monetary Fund estimates the Gulf economy will contract 4.8% this year before rebounding 9.1% in 2027, The National reported.